

Most observers of the industrial structure of the United States have noted the consolidation of industries, with one giant buying another. Many industries begin an early industry phase of new entrants, with many competitors, followed by a shakeout or a gradual consolidation. This has happened in industries as diverse as pharmaceuticals, banks, PC makers, and department stores. Might AI evolve in the same pattern?
In the late 1970s I did competitive analysis for a major department store company, May Department Stores, and we tracked at least 8 key competitors. Today there is one giant, Macy’s, which inherited almost all of those other companies through a chain of acquisitions and mergers. Only Dillard’s, Boscov’s, and Nordstrom, all relatively minor competitors back then, have remained independent.
A great example of consolidation is the airline industry. A few years ago, we produced a chart showing changes in industry leadership since 1950, one of our most popular charts. Today we present a better version of that chart, going all the way back to the origins of the industry almost a century ago, in 1930. Over that century, the industry went from 7 airlines to a peak of 32 in 1950, and now back down to 7 today.
Below the chart, we examine airline history in a little more depth.
Origins of the Industry
By the 1920s, courageous investors were starting to back the upstart airlines. While they were dependent for their survival on US Post Office airmail contracts, the airlines also began to carry passengers, who had to be pretty brave. Some observers felt that airlines would never become profitable carrying passengers, accidents were frequent and prices were high.
(For a more complete history of the airline industry, the politicization of contract awards in the Hoover and FDR administrations and the tempestuous “Airmail Scandal” of the 1930s, see my more comprehensive and fully illustrated video presentation.)
The initial companies often only flew a few routes between two or three cities. A larger, more ambitious effort was by Wiliam Boeing’s Seattle company, which flew from Seattle to Los Angeles and from San Francisco to Chicago. This map illustrates some of the larger airlines in 1929, before our chart begins, and before the real rise of the industry.

The following map shows those same 1929 carriers but identifies what airlines they became part of in later years.

In the early days, airlines and aircraft manufacturers were often the same company, as in Boeing’s case. General Motors and Ford both got involved in making planes and flying them. In the stock market boom of the roaring twenties that preceded the 1929 crash, Wall Street investment bankers helped put together giant holding companies.
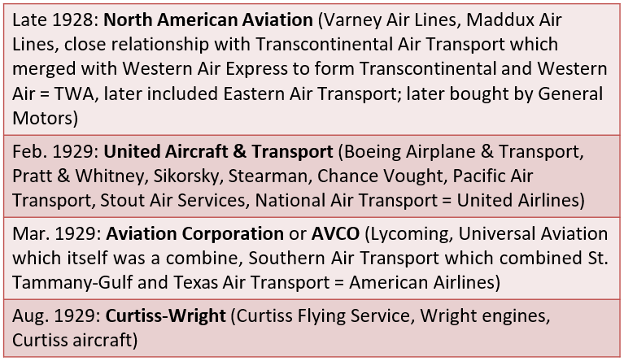
As part of the aforementioned Airmail Scandal, in 1934 the government forced separation of aircraft manufacturing and airline operation. The story of Boeing and United Aircraft is told here.
Expanding the Industry
In the relatively short period of twenty years, from 1930 to 1950, the number of airlines rose from 7 to 31. Mergers and organic route growth created the “Big Four” domestic giants (American, Eastern, Transcontinental & Western Air or TWA, and United).
The other big carrier was Pan American, endorsed by the US government as the national “flag carrier” to compete with the many international airlines, largely European and usually with heavy government support. Pan Am was not allowed to carry passengers between US cities but had dominance outside the US. When the airline industry was deregulated in 1978, Pan Am finally got the right to fly between American airports.
By 1950, oil equipment heir Howard Hughes had purchased Transcontinental & Western (1939), convinced the government that Pan Am could use some competition and received international flying rights from the federal regulators (1945). He appropriately renamed the airline Trans World Airlines (1950), keeping the TWA initials.
That twenty-year period also saw some of the smaller airlines and ones which did not exist in 1930 rise to “trunk airline” status: Northwest, Capital, Delta, National, Braniff, and Western. (The purchase of Capital by United in the early 1960s catapulted United ahead of American in size).
These companies were led by men who had been in the industry since the beginning and became legends in the industry. The full story of one of the greatest, American Airlines leader CR Smith, is told here.


The Local Service Airlines
The biggest rise in the number of airlines came from the creation of “local service” airlines. In the mid-1940s, the government experimented with the idea of allowing a new type of airline to bring air travel to smaller communities. The first of these began flying in 1945. The new airlines were subsidized by airmail contracts. Twenty such carriers were created over time, but they did not all survive and a few merged. By 1950, there were 15 and by the 1960s 13 survivors.
Each served a specific region. The largest in terms of passenger-miles were Allegheny based in Washington, Mohawk based in Utica, New York, Pacific based in San Francisco, and Ozark based in St. Louis. Frontier, based in Denver, also rose in size but perished in 1986. A new Denver-based Frontier arose in 1994 and continues to this day but is unrelated to the earlier local service airline. (Note that Florida was left out of the system due to lobbying and multiple Florida city service by larger carriers Eastern and National.)
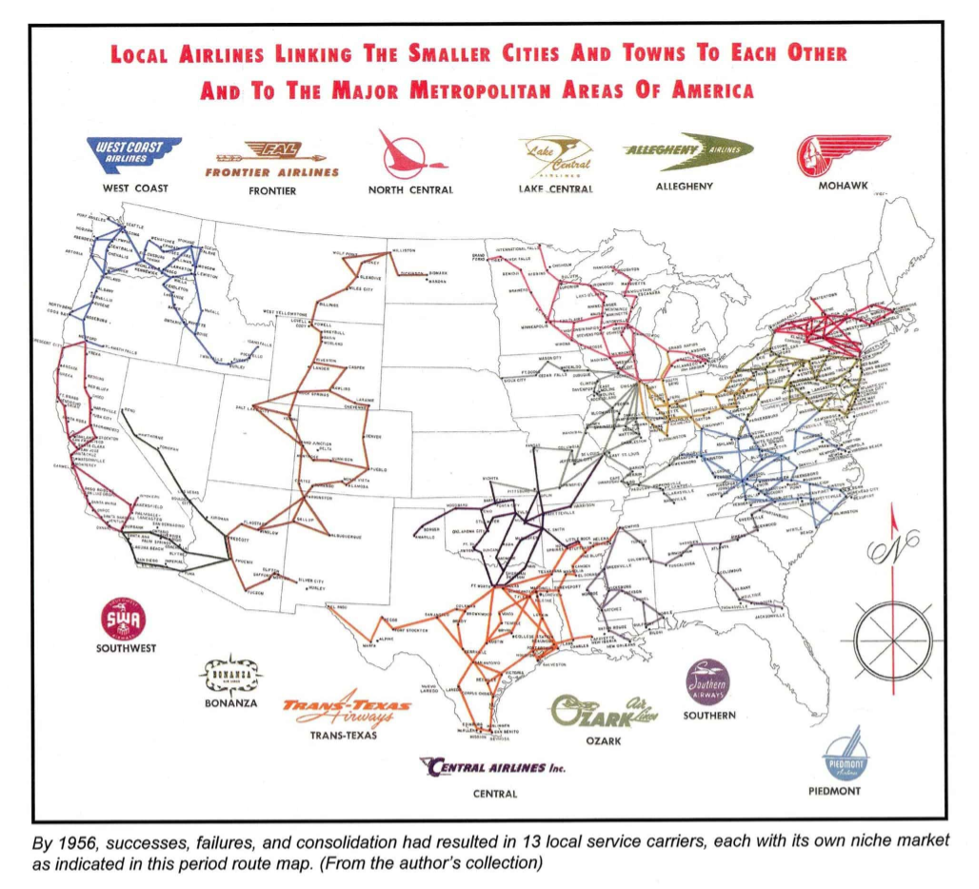
With natural route growth (as allowed by and limited by the Civil Aeronautics Board), by the mid-1960s a person could fly from coast to coast on these small carriers, but it would require a LOT of airplane changes and patience!

Allegheny began consolidating the local service carriers with the 1968 purchase of Indianapolis-based and employee-owned Lake Central, followed by Mohawk, and evolved into US Air, which later added Winston-Salem based Piedmont. Also in 1968, West Coast, Pacific, and Bonanza merged to form Air West. In 1979, Minneapolis-based North Central, one of the larger local service carriers, merged with Atlanta-based Southern to form Republic Airlines, which acquired the renamed Hughes Airwest in 1980. Republic was acquired by Northwest in 1986. None of the local service carriers survive today.
The Long Consolidation
The following pictures, taken from our animated chart, show the continuing consolidation of the industry. In 1972, for the first time, over half of American adults had ridden on an airline. Today that percent is 90%. See the dramatic rise of the total millions of passenger-miles of these airlines in the lower right corner of each picture.


The financial woes and collapse of industry pioneers Pan Am and Eastern are worthy of more complete stories. Both companies died in 1991.


The twenty-first century saw massive, headline-making consolidations, with American acquiring TWA in 2001, Delta taking over Northwest and United merging with Continental in 2010, and American buying USAir in 2015.

In recent months, United’s CEO has proposed the takeover of American, a merger certain to attract concerns by antitrust regulators. Over the years, Delta has emerged to be the most respected and well-run airline by most studies and Wall Street analysts. Southwest continues in its independent ways.
Until the 1970s and 1980s, these airlines were overwhelmingly domestic carriers. Today, the three largest have become major international competitors, each serving over 100 destinations in more than 60 nations. United gets about 41% of its revenue from international flights, Delta 30%, and American 27%. Even Southwest, originally a Texas-only intrastate carrier, now serves 14 destinations in 10 countries in the Caribbean, Central America, and Mexico.
Because of the wealth of the American economy and the size of the country, the US carriers have always been larger than the biggest foreign airlines, though the gap has closed over the years. Here is how global airlines compared in 1960 (excluding the Soviet Union’s Aeroflot, which claimed about 20% more passenger-miles than American Airlines):

Here is the same table for 2025:

Thus, we can see how the industry expanded and attracted new competitors, though strictly limited by the government until the 1970s deregulation. Over all these years, airline safety has improved and, on an inflation-adjusted basis, prices have come down.


It strikes us as somewhat amazing that federal regulation of airline pricing and routes by the Civil Aeronautics Board lasted as long as it did, and that it took courage on the part of President Jimmy Carter and Alfred Kahn to get it through Congress, finally freeing industry leaders to make the best decisions for their employees, passengers, and shareholders.
Nevertheless, the history of the industry has been turbulent. Fuel price spikes, wars, pandemics, and poor financial management have often afflicted the airlines. In many years the industry as a whole lost money. Only Southwest has remained reliably profitable, every year except during COVID. Unlike most of the giants, the company has never gone bankrupt.
Each airline has a fascinating story, worthy of further reading in the many books available, these two being among the best overall histories:
Airlines of the United States since 1914 by R.E.G. Davies (1988)
Airlines of the Jet Age: A History by R. E.G. Davies (2011)
The visually stimulating story of airline graphics is told here. The Northwestern University library has also compiled this nice visual story.
And if the airline industry consolidation from many to few is striking, how about the (also deregulated) railroad industry, which originated in literally hundreds if not thousands of small, short railroads? (More on that tale here, with a more recent update on the current possible big merger here.)

Gary Hoover
Executive Director
American Business History Center


